What Happens After Your Offer Is Accepted?
You found the house.
You wrote the offer.
You waited anxiously for the seller's response.
And then you get the text or phone call you've been waiting for: “They accepted your offer!”
Cue the celebration. But then, about five minutes later, you might have another thought:
“Ummm… now what?”
If you're a first-time home buyer, you're definitely not alone. Getting your offer accepted is a huge milestone, but it's not the finish line. It's actually the beginning of the under-contract period—the stretch of time between having your offer accepted and officially becoming the owner of the home.
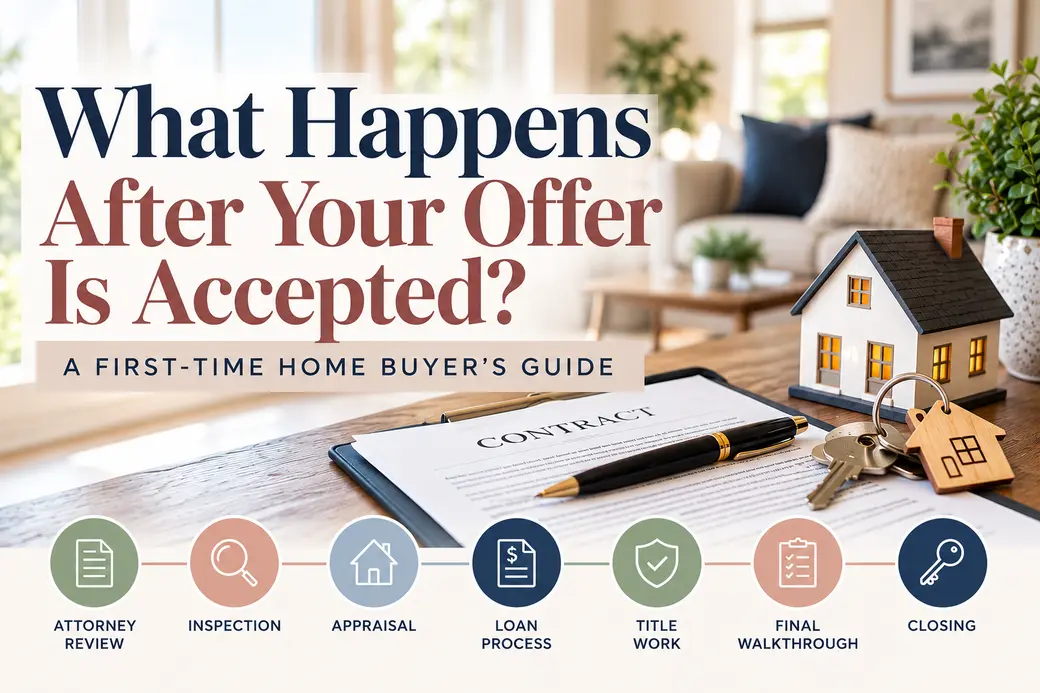
There are several important things that happen during this period, including inspections, attorney review, appraisal, loan processing, title work and eventually your final walkthrough and closing. The exact order and timing can vary based on your contract, financing and the property, but here's a general look at what you can expect.
First Things First: You're Under Contract!
Once your offer is accepted and the appropriate parties have signed the contract, you've moved from house hunting into the under-contract phase. This is when the deadlines in your purchase contract become especially important.
Your contract will spell out things like:
- Earnest money requirements
- Inspection provisions and deadlines
- Financing contingencies
- Appraisal provisions
- Closing date
- Other contingencies and obligations
This is one of those moments where you don't want to rely on something your cousin's neighbor's friend told you happened during their home purchase in 2019. Your contract controls your transaction. Your Realtor can help you understand the real estate process and your attorney can advise you about the legal aspects of your specific contract.
1. Earnest Money Is Deposited
One of the first things you'll likely deal with is your earnest money deposit. Earnest money is a deposit that demonstrates your good-faith commitment to purchasing the home. It's important to remember that earnest money is not the same thing as your down payment.
If the transaction closes, the earnest money is generally credited toward the funds you owe at closing. What happens to the deposit if the transaction doesn't close depends on the terms of your contract and the circumstances involved. That's why paying attention to deadlines and understanding your contingencies is so important.
👉 Related: What Is Earnest Money? A First-Time Home Buyer's Guide
2. Attorney Review
If you're buying a home in Illinois, attorney review is an important part of the process. During attorney review, your attorney reviews the purchase contract and can address legal issues and proposed changes according to the terms of your agreement. This is one of the biggest differences first-time buyers may notice when purchasing in Illinois compared with what they see on national real estate shows or hear from friends in other states.
And it's a good reminder that your real estate team has different roles.
- Your Realtor
Your Realtor helps guide you through the transaction, market considerations, negotiations and the real estate process. - Your Attorney
Your attorney provides legal advice and handles legal questions related to your contract and transaction. - Your Lender
Your lender handles the mortgage side of the transaction.
You want everyone communicating and doing their part. Teamwork makes the literal dream work!
3. Schedule Your Home Inspection
Next up: the inspection. A home inspection gives you an opportunity to learn more about the condition of the property you're purchasing.
An inspector may evaluate accessible areas and major systems such as:
- Roof
- Foundation
- Electrical
- Plumbing
- HVAC
- Windows and doors
- Attic
- Basement or crawl space
- Exterior
- Other accessible components
And here's something important: The inspection isn't a pass-or-fail test.
Every home has maintenance. Even a beautiful, well-maintained home may have items noted in an inspection report.
The purpose is to help you understand the home's condition and identify issues that may warrant further investigation, repairs, negotiation or other action depending on your contract. If your inspector recommends bringing in a specialist for something like a structural concern, sewer issue, radon, mold or another specific problem, that may become another step in the process.
4. Inspection Contingencies and Negotiations
So what happens if the inspection uncovers something significant? This is where your contract matters.
Depending on the terms of your agreement, inspection findings may lead to:
- Additional inspections
- Requests for repairs
- Credits
- Negotiations
- A decision to proceed
- Or, in certain circumstances, termination of the contract
But here's something I want first-time buyers to hear: An inspection report is not a wish list.
You're not necessarily going to ask the seller to replace every 15-year-old appliance because the inspector noted that it's old. The goal is to understand the condition of the property and determine whether there are significant issues that affect your decision to move forward.
Your Realtor can help you navigate the real estate and negotiation side of the process, while your attorney can advise you regarding the contract and your legal rights.
5. Your Mortgage Process Keeps Moving
Your offer being accepted doesn't mean your mortgage is finished. Actually, this is when the lender gets even more involved. Your lender will continue working on your specific loan for the property you are purchasing.
That may involve:
- Verifying income
- Reviewing assets
- Checking documentation
- Ordering the appraisal
- Processing the loan
- Underwriting
- Requesting additional documentation
- Preparing the loan for closing
You may feel like you've already handed your lender approximately 47 documents. And then they ask for three more.
Respond as quickly as you can! Delays in providing requested documentation can create unnecessary stress later in the transaction.
6. The Appraisal
If you're financing the home, your lender may require an appraisal. And this is where it's important to remember the difference between the inspection and appraisal.
The inspection asks: “What's the condition of this home?”
The appraisal asks: “What is this property worth for the purposes of the lending transaction?”
They are completely different. An appraisal considers the property and relevant market information to develop an opinion of value. Ideally, the appraisal supports the purchase price.
But what if it doesn't? A low appraisal doesn't automatically mean your purchase is over. Depending on your financing, contract and circumstances, there may be several possible paths forward, which could include renegotiation or other solutions.
Your Realtor and lender can help you understand the options available in your situation.
7. Title Work Happens Behind the Scenes
Here's another part of the transaction buyers don't always see: Title work.
The title company or other professionals handling the closing will work through the title process to identify issues that need to be addressed before the property can be transferred. This can involve researching the property's ownership history and looking for things such as outstanding liens, claims or other title issues. Most of the time, this happens quietly behind the scenes.
And honestly? Quiet is good!
But if a title issue does come up, it may need to be resolved before closing. This is one reason title work is an important part of protecting the buyer and making sure the seller can transfer the property as required.
8. Your Loan Goes Through Underwriting
Now we're getting closer to the finish line. Underwriting is where your lender evaluates your loan application and supporting documentation to determine whether the loan meets the lender's requirements. You may be asked for additional information.
Again. ---Yes, even though you already sent it. Try not to take it personally. Your lender may need updated documents or clarification as the loan moves toward final approval.
During this stage, avoid making major financial changes without talking to your lender first!
That means think twice before:
- Financing a new car
- Opening new credit cards
- Taking on significant new debt
- Making large unexplained deposits
- Changing jobs
- Making other major financial moves
Your lender can tell you whether something could affect your mortgage. When in doubt, ALWAYS ask questions before you act.
9. Your Closing Disclosure Arrives
As you get closer to closing, you'll receive your Closing Disclosure. This document provides important details about your mortgage and the costs associated with your transaction. For most covered mortgage transactions, the buyer must receive the Closing Disclosure at least three business days before closing. This is your opportunity to review the final numbers before you sit down at the closing table.
Take a look at things like:
- Loan amount
- Interest rate
- Monthly payment
- Closing costs
- Cash to close
- Credits
- Prepaid expenses
- Other transaction details
Don't understand something? Ask.
Don't be embarrassed to say, “Can you explain this?”
You are making a very large financial commitment. You deserve to understand what you're signing.
10. The Final Walkthrough
You're almost there. Before closing, you'll typically have a final walkthrough of the property.
This isn't another full inspection. Instead, it's your opportunity to make sure the home is generally in the condition you expect based on your agreement.
Depending on your contract, you may be checking that:
- Agreed-upon repairs were completed
- Items included in the sale are still present
- The home hasn't experienced new damage
- The property is substantially as expected
- The seller has removed their belongings as required
If something doesn't look right, tell your Realtor. Don't wait until after closing to mention it.
11. Closing Day!
And finally… It's closing day.
You'll sign the documents required to complete the purchase and your mortgage. Once the transaction is completed and the applicable closing process is finished, the home becomes yours.
And then comes the part you've been waiting for: THE KEYS. 🏡🔑
That moment when you're standing in your new home thinking:“Holy crap. We actually did this.”
It's a pretty good feeling.
What Can Go Wrong Between Contract and Closing?
Here's the part nobody wants to talk about—but every buyer should understand. An accepted offer doesn't mean nothing can go wrong.
You could run into:
- Inspection issues
- Appraisal problems
- Financing delays
- Title issues
- Unexpected property damage
- Documentation problems
- Contract disputes
- Delays with another party in the transaction
That doesn't mean you should spend the next 30 days panicking. It means you should stay responsive and communicate with your team. If something changes, tell your Realtor or lender. If you don't understand something, ask. If someone sends you suspicious wiring instructions, verify them independently (wire fraud is VERY real!)
The goal isn't to eliminate every possible problem. It's to have the right people helping you navigate them if they arise.
What Should You NOT Do While You're Under Contract?
This deserves its own section because it can save buyers a LOT of unnecessary stress. Once you're under contract, boring is beautiful.
Seriously. Keep your finances as stable as possible until closing.
Don't finance a new car.
Even if you desperately want that shiny new SUV.
Don't open a bunch of new credit cards.
That furniture store's “no interest for 18 months” offer can wait.
Don't make major financial changes without talking to your lender.
Your lender would much rather answer a question beforehand than try to fix a problem afterward.
Don't ignore requests from your lender.
If they ask for documentation, get it to them.
Don't miss contractual deadlines.
Your contract isn't a suggestion.
And NEVER blindly wire money.
Verify wiring instructions with your title company, attorney or other trusted closing professional using a known phone number. Real estate wire fraud is very real, and your earnest money and closing funds are too important to take chances with.
Buying a Home in Plainfield or the Southwest Suburbs?
If you're buying a home in Plainfield, IL, or one of the surrounding Southwest Suburbs like Joliet, Lockport, Shorewood, Romeoville or Oswego, this general roadmap will probably look familiar.
But here's the important thing: Every transaction is different.
Your timeline may look different from your neighbor's.
Your inspection period may be different.
Your financing may be different.
Your contract may have different provisions.
Your closing date may move.
That's why the best approach is to understand the overall process, while letting your Realtor, lender, attorney and title professionals guide you through the specifics of your transaction.
Final Thoughts
Getting an offer accepted is exciting. It's also when the real work begins.
From attorney review and earnest money to inspections, appraisal, financing, title work and the final walkthrough, there are quite a few moving pieces between “They accepted!” and “Here are your keys.”
If you're a first-time buyer, don't feel like you have to memorize every step before you start.
Just remember the general flow:
Offer accepted → Attorney review → Earnest money → Inspection → Loan processing → Appraisal → Title work → Underwriting → Closing Disclosure → Final walkthrough → Closing
And when you aren't sure what's happening? Ask.
That's what your real estate team is there for. Buying a home is a big deal. You deserve to know what's happening with your money, your contract and your future home every step of the way.
And then, finally…
Welcome home. 🏡❤️
Categories
Recent Posts